
Category: Term Life
-

Introduction Term life insurance is designed to pay a death benefit if the insured person dies while the policy is in force, but that does not mean every claim is automatically payable in every circumstance. The important distinction is that there is no single universal list of life insurance exclusions that applies to every policy…
-

Introduction Return of premium (ROP) term life insurance adds an appealing feature to temporary life insurance: if you outlive the specified term and meet the policy requirements, part or all of the eligible premiums you paid may be returned to you. That can sound like an obvious upgrade over regular term insurance, but there is…
-
Introduction Starting or raising a family can create several financial responsibilities at the same time: housing, childcare, everyday expenses, debt and future education costs. Life insurance can help protect those plans if a parent or caregiver dies, but there is no universal coverage amount that every young family should buy. A household with one income,…
-
Introduction Term life insurance can provide a large death benefit during the years when your family, mortgage or other financial obligations create the greatest need for protection. But there is no single term life insurance company that is best for every applicant. One company may offer a 40-year term. Another may allow a particularly large…
-

Introduction Having type 1 or type 2 diabetes does not automatically prevent you from qualifying for life insurance. But diabetes can affect underwriting. Insurers may look at how long you have had the condition, how it is treated, your recent and historical A1C results, whether complications are present and your overall health. That means two…
-
Introduction Smoking does not automatically prevent you from getting life insurance. It can, however, have a major effect on the underwriting class and premium you are offered. The complication is that “smoker” does not mean exactly the same thing at every life insurance company. An insurer may distinguish between: The amount and frequency of use…
-
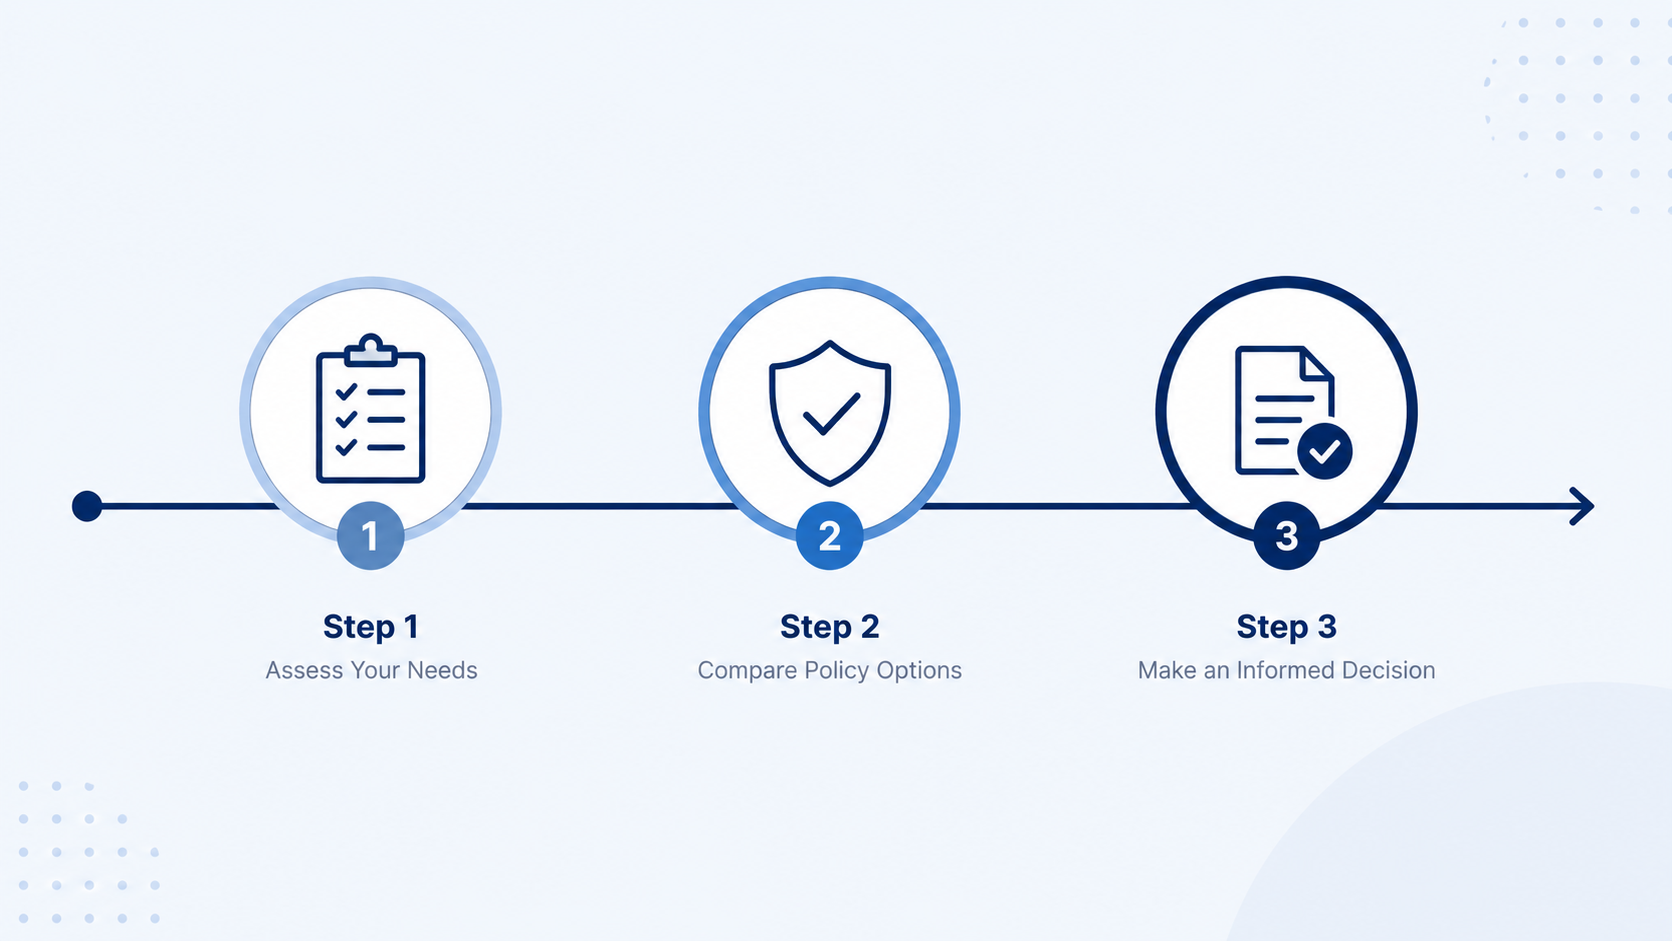
Introduction Choosing between a 10-, 20- and 30-year term life insurance policy is not simply a question of finding the cheapest premium. The term should ideally cover the years during which your death would create a significant financial problem for someone else. A 10-year policy may fit someone approaching retirement or paying off the final…
-
Introduction Term life and whole life insurance can both provide a death benefit, but they are designed to solve different types of financial problems. Term life provides coverage for a defined period. Whole life is permanent insurance designed to remain in force for life when required premiums are paid and policy conditions are satisfied. Whole…