

Introduction
Getting life insurance without a medical exam no longer necessarily means accepting a tiny death benefit or guaranteed-issue policy.
Some traditional insurers now use accelerated underwriting to offer qualifying applicants millions of dollars of term coverage without a paramedical exam, blood draw or urine sample. Digital platforms can also provide a completely online application without requiring an exam.
But there is an important catch:
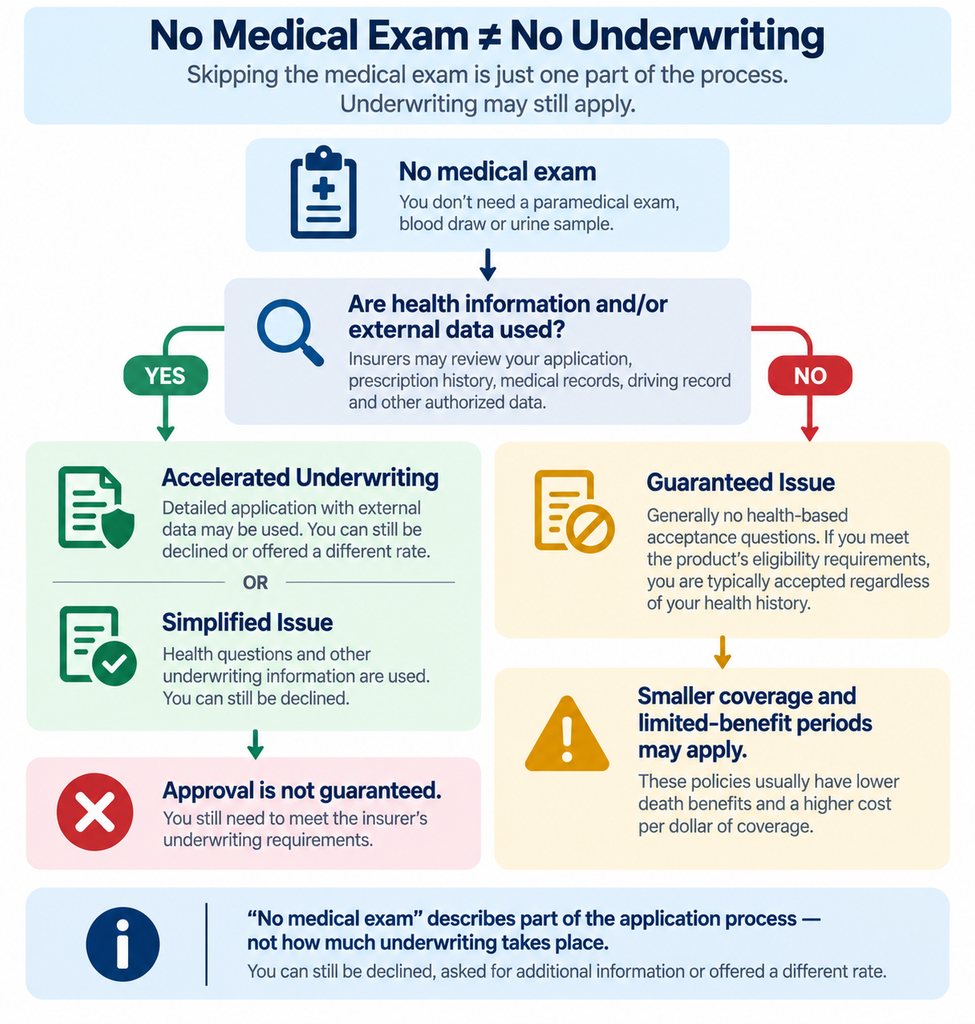
No medical exam does not mean no underwriting.
An insurer may still evaluate your health history, prescriptions, driving record, application answers and other authorized data. You can still be routed to additional underwriting or declined.
Quick answer: Banner Life currently offers one of the largest accelerated no-exam opportunities in this comparison, with eligible applicants ages 20–60 considered for up to $5 million of OPTerm coverage. Pacific Life offers up to $3 million through its accelerated PAL+ pathway. Ladder provides a fully digital no-exam process for applications up to $3 million. Ethos offers online no-medical-exam policies through multiple carrier partners. Mutual of Omaha provides simplified-issue Term Life Express for smaller coverage needs, while AARP/New York Life provides a no-physical-exam option designed specifically for eligible older adults.
No Medical Exam Does Not Always Mean the Same Thing
Before comparing companies, identify which underwriting process you are actually looking at.
| Underwriting Type | Medical Exam | Health Information | Can You Be Declined? | Typical Trade-Off |
|---|---|---|---|---|
| Accelerated underwriting | May be waived | Detailed application plus authorized external data | Yes | Can provide substantial traditional coverage without an exam for qualifying applicants |
| Simplified issue | Usually no traditional exam | Health questions and other underwriting information | Yes | Easier process but coverage/rate classes may be more limited |
| Guaranteed issue | No | Generally no health-based acceptance questions | Generally not for health, if product eligibility is met | Smaller benefits, higher cost per dollar and possible limited-benefit period |
These categories should not be treated as synonyms.
Someone who qualifies for $1 million through accelerated underwriting is buying a very different product from someone purchasing $20,000 of guaranteed-issue whole life.
How We Selected These No-Exam Options
We did not select companies based on which one advertises the fastest approval or lowest sample premium.
For this 2026 comparison, we reviewed current insurer and provider materials and considered:
- Published no-exam coverage limits
- Age eligibility
- Underwriting method
- Term and coverage flexibility
- Whether the exam is truly waived or only potentially waived
- Availability of larger death benefits
- Conversion options
- Digital application experience
- Options for older applicants
- Current product documentation
We also distinguish between insurance companies and digital agencies/platforms.
Banner Life, Pacific Life, Mutual of Omaha and New York Life are insurers.
Ladder and Ethos are licensed platforms or agencies that distribute policies issued by insurance companies.
That distinction matters because the company handling the application is not always the company ultimately responsible for the policy and claim.
Best No-Medical-Exam Life Insurance Options at a Glance
| Provider | Option | Published No-Exam Opportunity | Best Reason to Investigate |
|---|---|---|---|
| Banner Life | OPTerm accelerated underwriting | Up to $5 million for qualifying ages 20–60 | Very high accelerated term limit |
| Pacific Life | PL Promise Term through PAL+ | Up to $3 million for qualifying ages 18–60 | Traditional term with strong accelerated pathway |
| Ladder | Digital term life | No exam for applications up to $3 million | Fully digital process and flexible coverage management |
| Ethos | Multi-carrier digital life insurance | Term coverage available up to $3 million without a medical exam, depending on product | Fast online application across multiple carrier partners |
| Mutual of Omaha | Term Life Express | Simplified issue with no paramed exam | Smaller coverage needs and later-age availability |
| AARP/New York Life | Level Benefit Term | Up to $150,000 with no physical exam | Older eligible AARP members |
“No exam” does not guarantee approval unless the product is specifically guaranteed issue.
Coverage, underwriting and availability can vary by state and applicant.
Banner Life — Worth Investigating for High No-Exam Term Coverage
Banner Life has expanded accelerated underwriting significantly.
Its current OPTerm accelerated-underwriting program allows qualifying applicants ages 20–60 to be considered for up to:
$5 million
of coverage.
Banner states that qualifying applicants may receive:
- An instant decision
- An exam-free underwriting outcome
- An APS-free outcome in some cases
Applicants who do not qualify for the accelerated route can move into another appropriate underwriting pathway.
That is important.
Applying for $5 million does not mean Banner guarantees $5 million without an exam.
Eligibility can depend on:
- Age
- Height and weight
- Medical history
- Prescription history
- Financial justification
- Driving history
- Lifestyle factors
- Information found through authorized third-party data
Banner also currently provides an exam-free pathway for some applicants ages 61–70 for amounts up to $500,000, although an attending physician statement may be required.
Why Banner stands out
The combination of a large accelerated-underwriting limit and OPTerm’s wide term menu makes Banner particularly interesting for applicants who need substantial protection but want the possibility of avoiding a traditional medical exam.
OPTerm currently offers:
- 10 years
- 15 years
- 20 years
- 25 years
- 30 years
- 35 years
- 40 years
Not every applicant will qualify for every term or accelerated pathway.
Maximum issue age falls as the selected term becomes longer.
Pacific Life — Worth Investigating for Up to $3 Million Through PAL+
Pacific Life’s PL Promise Term uses Pacific Accelerated Life+, or PAL+.
Its accelerated pathway currently offers qualifying applicants:
Up to $3 million
of PL Promise Term coverage without a medical exam or attending physician statement.
The published accelerated pathway currently applies to ages:
18–60
and requires eligibility for Standard or better underwriting classes.
If the applicant does not qualify for accelerated underwriting, Pacific Life can route the application toward modified or traditional underwriting.
Again, that is why this is not the same as guaranteed no-exam approval.
PL Promise Term itself offers
- 10-year term
- 15-year term
- 20-year term
- 25-year term
- 30-year term
- Coverage beginning at $50,000
- Conversion opportunities subject to policy rules
Pacific Life therefore deserves consideration if you want a traditionally underwritten term product but would prefer the possibility of avoiding the medical exam.
Ladder — Worth Investigating for a Fully Digital Term Process
Ladder takes a different approach.
Ladder is a digital life insurance agency, not the insurance carrier itself.
Its current term policies are issued by partner insurers, with product availability varying by state.
Ladder currently states that applications for:
$3 million or less
do not require a medical exam.
Applicants still answer health questions.
For applications above $3 million, Ladder may request a health check.
In most states, Ladder currently offers total coverage from:
$100,000 to $8 million
and generally accepts applications from ages:
20–60.
That means the $3 million figure is specifically important as the current no-exam threshold, not the total maximum amount available through Ladder.
Why Ladder stands out
The application is designed to be completely digital for qualifying no-exam amounts.
Ladder also allows existing policyholders to reduce their coverage as their needs decline.
Increasing coverage requires additional application and underwriting rather than simply clicking a button and automatically receiving more insurance.
Ladder can therefore be interesting if you value:
- A digital application
- No paramedical exam up to the published threshold
- Term coverage rather than small guaranteed-issue insurance
- The ability to reduce coverage later
But underwriting still applies.
Ethos — Worth Investigating for a Multi-Carrier Online Application
Ethos is also a digital platform rather than a single insurance company.
Ethos works with multiple insurance carriers, including companies such as Banner Life, Protective, TruStage, Ameritas and others depending on the policy.
Its current consumer platform advertises:
- No medical exams
- Online health questions
- Term coverage up to approximately $3 million depending on product
- A fully online application
- Multiple life insurance product types
This creates an important distinction from applying directly with one insurer.
With Ethos, the digital platform can match eligible applicants with products issued by its carrier partners.
Why Ethos stands out
Ethos may be especially relevant if you:
- Want to complete the process online.
- Strongly prefer avoiding a physical exam.
- Want to see coverage available through more than one carrier ecosystem.
- Need term coverage rather than only a small guaranteed-issue policy.
However, approval is still based on underwriting for products that use health information.
“No exam” does not mean Ethos ignores your medical history.
Applicants may still be asked about:
- Personal medical history
- Family medical history
- Prescription medications
- Tobacco or nicotine use
- Driving or legal history
- Lifestyle
- Employment and financial information
The issuing insurer — not Ethos itself — is ultimately responsible for the insurance contract.
Mutual of Omaha — Worth Investigating for Simplified-Issue Term
Mutual of Omaha’s Term Life Express provides a useful example of simplified-issue insurance rather than accelerated traditional underwriting.
The product currently uses:
- No paramedical examination
- No blood draw
- No urine collection
- A streamlined health-information process
Term options currently include:
- 10 years
- 15 years
- 20 years
- 30 years
Current consumer materials publish maximum face amounts that vary by age:
Ages 18–50: up to $550,000
Ages 51–60: up to $450,000
Ages 61–75: up to $350,000
Actual availability and maximum term length also depend on age, tobacco status and state.
Why Mutual of Omaha stands out
Term Life Express can be useful when someone wants a more modest death benefit without going through the full traditional underwriting process.
It also extends into older age ranges than several large accelerated-underwriting programs.
But simplified underwriting has trade-offs.
Do not compare $500,000 of simplified-issue insurance with $500,000 of accelerated traditional insurance solely on application convenience.
Compare the:
- Actual premium
- Coverage period
- Rate structure
- Riders
- Conversion options
- Underwriting result
The easiest application is not necessarily the best contract.
AARP/New York Life — Worth Investigating for Older Applicants
AARP’s Level Benefit Term Life Insurance is underwritten by New York Life and uses a different no-exam structure.
Eligible AARP members can currently apply for up to:
$150,000
without a physical medical exam.
Acceptance is still based on health and other information.
Current eligibility generally includes AARP members ages 50–74 and qualifying spouses or partners ages 45–74, subject to product and state rules.
Coverage can continue to age 80.
But there is an important trade-off:
The premium is not level all the way to age 80.
Current rates increase as the insured enters new five-year age bands.
That makes this policy very different from a conventional 10- or 20-year level-premium term policy.
Why AARP/New York Life stands out
It may be worth investigating if:
- You are an eligible older applicant.
- You need $150,000 or less.
- Avoiding a physical exam is important.
- You understand that premiums increase with age.
- A term product continuing to age 80 matches your need.
Do not choose it simply because AARP membership makes the product familiar.
Compare the total expected premium path with other coverage you can qualify for.
What Does an Insurer Check If There Is No Exam?
Skipping blood and urine does not make the underwriting process blind.
The NAIC explains that accelerated-underwriting systems can use information from external sources in addition to the application.
Depending on the insurer and your authorization, that can include:
- Prescription drug history
- Motor vehicle records
- Medical Information Bureau information
- Electronic health information
- Credit-related information where permitted and used
- Application disclosures
- Other authorized data
Banner, for example, specifically states that its accelerated process considers applicant disclosures, prescription history, medical claims information and other third-party data.
This explains how an insurer can potentially approve substantial coverage without sending someone to a paramedical appointment.
The medical exam has disappeared.
The risk assessment has not.
No Exam Does Not Mean Guaranteed Approval
This is the biggest misconception to avoid.
Imagine an applicant selects:
$2 million term coverage — no medical exam advertised
That does not necessarily mean:
Fill in the application → automatically receive $2 million.
Possible outcomes can include:
Approved through accelerated underwriting
The exam is waived and the applicant receives an offer.
Additional information requested
The insurer may need records or other evidence.
Moved to traditional underwriting
A medical exam or laboratory work may be required.
Offered a different rate class
The applicant may qualify, but at a different premium.
Declined or postponed
Health or other underwriting factors may prevent immediate approval.
The exact possibilities depend on the insurer.
Guaranteed acceptance is a separate category.
Is No-Medical-Exam Life Insurance More Expensive?
Not always.
This depends heavily on the underwriting type.
With accelerated underwriting, the insurer may simply be using alternative data and technology to evaluate someone who otherwise could have gone through traditional underwriting.
With simplified issue, the insurer collects less medical information and may price that additional uncertainty differently.
The NAIC notes that simplified underwriting can generally involve higher premiums in exchange for avoiding more extensive medical requirements.
Guaranteed-issue coverage has another risk structure entirely.
Therefore, do not use a universal rule such as:
“No-exam insurance costs 20% more.”
There is no reliable percentage that applies across products and applicants.
Compare real quotes.
When Taking the Medical Exam May Still Be Worth Considering
Avoiding the medical exam is convenient, but convenience should not become the only selection criterion.
Suppose you are:
- Healthy
- Comfortable completing an exam
- Applying for a large death benefit
- Shopping primarily for the best final premium
It may be worth comparing no-exam options with fully underwritten policies.
Traditional underwriting can give the insurer more information about your health.
Depending on your profile and the insurers involved, that may produce different coverage or pricing opportunities.
The correct question is not:
“How do I avoid the exam at all costs?”
It is:
“What policy gives me the right coverage and contract at an acceptable premium, and can I obtain it without an exam?”
When No-Exam Coverage Can Be Particularly Useful
A no-medical-exam option may deserve extra consideration when:
- You strongly prefer a digital application.
- Scheduling a paramedical exam would be difficult.
- You qualify for a competitive accelerated-underwriting pathway.
- You need coverage relatively quickly.
- The no-exam product provides the death benefit and term you actually need.
- You are an older applicant using a simplified-issue product.
- You understand that health questions and underwriting can still apply.
Speed alone should not determine the choice.
Coverage may remain in force for decades, so the policy itself matters much more than saving a few days during the application.
What If You Have a Health Condition?
Do not assume a health condition automatically makes guaranteed issue your best option.
Accelerated-underwriting eligibility may be more restrictive for certain medical histories, but failing to qualify for acceleration does not necessarily mean you cannot obtain traditionally underwritten coverage.
You could be:
- Moved to full underwriting
- Asked for medical records
- Asked to complete an exam
- Offered coverage at a different rate
- Better suited to another insurer
If you have a significant medical history, our guide to life insurance for seniors with health conditions explains why different insurers can evaluate the same diagnosis differently.
Someone with diabetes should also avoid relying on a generic no-exam recommendation without comparing insurers that specifically document their approach to life insurance for diabetics.
How Much No-Exam Coverage Do You Need?
Do not select your death benefit based on the insurer’s maximum.
Banner allowing an eligible applicant to pursue $5 million through accelerated underwriting does not mean that applicant needs $5 million.
Likewise, a $150,000 no-exam product should not be purchased if your household needs $750,000 simply because the application is easier.
First calculate how much life insurance you actually need.
Then look for no-exam products capable of addressing that amount.
A basic framework is:
Financial obligations
− existing resources
= potential coverage gap
Your insurance need should determine the product search.
The product limit should not determine your insurance need.
No-Exam Life Insurance Comparison Worksheet
When comparing policies, fill this out using the actual product information and final offer.
| Question | Option A | Option B | Option C |
|---|---|---|---|
| Provider | ________ | ________ | ________ |
| Issuing insurer | ________ | ________ | ________ |
| Policy type | ________ | ________ | ________ |
| Death benefit | $________ | $________ | $________ |
| Coverage duration | ________ | ________ | ________ |
| Premium | $________ | $________ | $________ |
| Underwriting type | ________ | ________ | ________ |
| Medical exam guaranteed to be waived? | Yes / No | Yes / No | Yes / No |
| Health questions? | Yes / No | Yes / No | Yes / No |
| Additional records possible? | Yes / No | Yes / No | Yes / No |
| Final underwriting class | ________ | ________ | ________ |
| Conversion option | ________ | ________ | ________ |
| Important riders | ________ | ________ | ________ |
| Premium remains level? | ________ | ________ | ________ |
| State limitations | ________ | ________ | ________ |
When comparing options, check the provider and the issuing insurer separately, especially with digital agencies such as Ladder or Ethos.
How to Compare No-Exam Quotes Fairly
Use the same:
Applicant
Coverage amount
Term length
State
Nicotine status
Quote date
and, when possible, comparable underwriting classes.
Then compare the final approved offers rather than only the first online estimate.
A preliminary online quote is not necessarily the premium you will receive after underwriting.
Also compare the no-exam policy against at least one traditionally underwritten alternative if you are willing and able to complete an exam.
You may discover that the convenience comes with little trade-off.
Or you may discover that another product fits significantly better.
There is no universal result.
Which No-Exam Option Should You Investigate First?
A needs-based approach is more useful than ranking the companies from 1 to 6.
Need a large traditional term death benefit?
Banner Life and Pacific Life deserve a closer look because their accelerated pathways currently reach into the millions for qualifying applicants.
Want a completely digital term application?
Ladder and Ethos are natural places to investigate.
Need a smaller simplified-issue term policy?
Mutual of Omaha Term Life Express may fit the search.
Applying later in life for $150,000 or less?
Eligible AARP members may want to compare New York Life’s AARP term offering with other senior options.
Have serious health issues that make ordinary underwriting difficult?
You may eventually need simplified or guaranteed-acceptance coverage, but check whether traditionally underwritten options remain available before assuming that.
The easiest application and the best policy are not always the same thing.
Frequently Asked Questions
What is the best no-medical-exam life insurance in 2026? There is no universal winner. Banner Life currently has a particularly large accelerated-underwriting limit, Pacific Life offers up to $3 million through PAL+ for eligible applicants, Ladder and Ethos emphasize digital applications, and Mutual of Omaha and AARP/New York Life provide useful alternatives for smaller or older-applicant coverage needs.
What is the highest no-exam coverage amount in this comparison? Banner Life currently allows qualifying applicants ages 20–60 to be considered for up to $5 million of OPTerm coverage through accelerated underwriting. That is an eligibility ceiling, not guaranteed exam-free approval for every applicant.
Can I really get $3 million of life insurance without a medical exam? Potentially. Pacific Life currently advertises up to $3 million through its accelerated PAL+ pathway for qualifying applicants ages 18–60, and Ladder states that applications for $3 million or less do not require its health check. Their underwriting processes and eligibility rules are different.
Does no medical exam mean no health questions? Usually not. Accelerated and simplified underwriting can require substantial health information even when no physical exam is performed.
Does no exam mean guaranteed approval? No. Accelerated and simplified-issue applicants can still be declined, postponed, offered another rate or moved to additional underwriting. Guaranteed-issue insurance is a separate product category.
Is no-exam life insurance more expensive? Not universally. Accelerated underwriting and simplified issue work differently. Compare actual final premiums rather than applying a generic surcharge percentage.
Can people with health conditions get no-exam life insurance? Sometimes. Eligibility depends on the condition, insurer and underwriting process. A health condition can make accelerated underwriting unavailable without necessarily making all life insurance unavailable.
Can seniors buy life insurance without an exam? Yes. Products such as Mutual of Omaha Term Life Express and AARP/New York Life provide no-paramedical-exam routes for eligible older applicants, while guaranteed-issue permanent products are also available from some insurers.
Is Ladder an insurance company? Ladder Insurance Services is a licensed digital agency. Its current policies are issued by partner insurance companies, which are responsible for their respective policies and claims.
Is Ethos an insurance company? Ethos operates as a licensed producer/platform and distributes insurance issued by partner carriers. Check the issuing insurer shown on the policy you are offered.
Should I avoid a medical exam if I can? Not necessarily. Avoiding the exam can make the process easier, but the policy’s price, coverage, term, conversion rights and underwriting result are more important than application convenience alone.
How quickly can no-exam life insurance be approved? Accelerated and digital underwriting can sometimes produce very fast decisions, but there is no universal approval time. Medical records, additional underwriting or other requirements can extend the process.


